Iron Ore Fines
Second-tier fines 58–65% Fe priced off the 61% Fe index with a differential
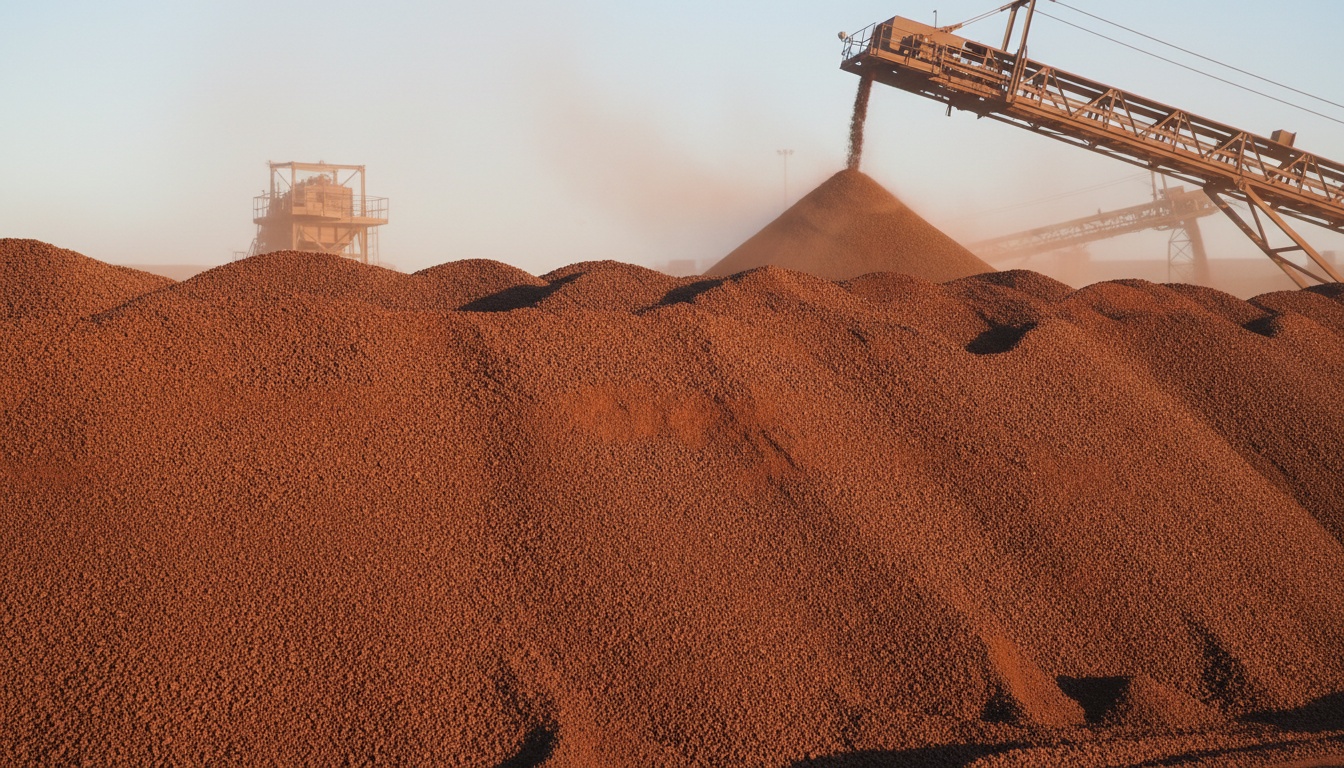
Iron ore fines are bought on iron content and sold on everything else. Fe (58–65% for the second-tier trade) sets the headline, and the price is written as the 61% Fe CFR China index plus or minus a differential that the gangue decides: silica (3–8%), alumina (1–4%, with the alumina-to-silica ratio watched by sinter plants because high alumina thickens slag and raises coke rate), phosphorus (0.03–0.12%, the number that pushes a high-phosphorus ore into a discount), sulphur (≤ 0.05%) and loss on ignition (2–10%, high in goethitic and lateritic ores and effectively iron you pay freight on and then lose in the furnace). Free moisture (8–12%) matters twice over — once as paid weight and once as a carriage question, because fines with moisture above their transportable moisture limit can liquefy at sea, so a certificate of the TML and a moisture declaration within seven days of loading are conditions of shipment, not paperwork. Size is 0–10 mm for sinter feed; anything finer than 45 microns in quantity goes to a pellet plant instead. The Platts IODEX benchmark moved from a 62% to a 61% Fe basis on 2 January 2026, so older contracts written against 62% need their differentials re-read. The 2025 export declarations under HS 2601.11 (fines and lump) show where the tonnage sits and who sells it. Australia (921.5 million MT) and Brazil (392.6 million MT) are the majors' book, the benchmark the second tier prices against and not a market CBIL claims a seat in. South Africa declared 65.5 million MT at an average USD 93/MT, most of it from the large Northern Cape miners through Saldanha, with junior miners shipping a smaller share on their own rail allocations. Canada's 47.4 million MT comes from the large Labrador Trough producers. India declared 22.1 million MT at USD 59/MT, and its destination list is the plainest picture of a second-tier fines book: China 21.4 million MT, then Nepal 0.23, Indonesia 0.20 and Malaysia 0.08 million MT. Malaysia declared 20.0 million MT at USD 59/MT, but it imported 21.4 million MT in the same year, 17.9 million MT of it from Brazil: most of what leaves Malaysia is Brazilian ore re-shipped from Vale's Teluk Rubiah distribution terminal, and Malaysia's own mines in Pahang, Terengganu and Johor account for a small share (about 1.8 million MT in 2024, per Shanghai Metals Market).
CBIL is a commodity brokerage company and does not pretend to broker Pilbara or Carajás term tonnage; the majors sell that themselves, on their own contracts, to mills they have known for decades. The page is for the second tier: India's non-captive east-coast exporters, South African junior miners and Malaysia's own mines, with spot and short-term parcels of 58–65% Fe fines, and the sinter plants, pellet plants and traders that take them. That market is priced by differential, and the differential is settled on the surveyor's certificate: SGS, Intertek or Bureau Veritas sampling at the load port to ISO 3082, chemistry to ISO 2597 and ISO 11536 for loss on ignition, moisture to ISO 3087, with the load-port certificate governing unless the contract writes in discharge-port re-analysis. Parcels are structured in Supramax and Ultramax lots out of Paradip, Haldia, Visakhapatnam and Kuantan, and in Panamax or Capesize lots out of Saldanha where the load and discharge ports take it, on FOB and CFR terms, and because CBIL also runs a chartering desk (LaycanDesk) the freight is quoted alongside the cargo so a CFR offer and an FOB-plus-fixture number are comparable on the same day. Indian loadings carry a condition of their own: under India's November 2022 notification, export duty is 30% on lumps and fines of 58% Fe and above, and nil below 58% Fe and on pellets, which is one reason so much of India's China trade is low-grade fines. Send your Fe floor, the silica, alumina and phosphorus ceilings your sinter plant runs to, and the discharge-port draft, and we will work the origin to them.
Need the ship as well? Our chartering desk prices Chattogram to Vietnam mill scale freight on LaycanDesk.
Excluded origins are not offered, including product re-exported, blended or re-processed through a third country. Every lot moves with a certificate of origin naming the producing plant, mine or grower country, and nothing is quoted before the seller and loading point are known.
Indicative reference
$55–100 USD / MT
as at September 2026
Reference level only — not an offer, and reviewed quarterly. Levels shown are as at September 2026. Firm pricing is quoted per RFQ, subject to volume, terms and inspection.
Typical Specification
Specifications are indicative and adjusted to the agreed contract and destination requirements. Final spec confirmed on COA / SGS.
Available Grades
Applications
- Sinter plants (blast-furnace burden)
- Pellet plants (concentrate feed)
- Ore blending at import terminals
- Direct-reduction pellet feed (high-grade concentrate)
Category
Metals & Recycled Scrap
Incoterms
FOB · CFR
Pricing basis
USD / MT
Inspection
SGS / Intertek at load port
Iron Ore Fines — buyer questions
How is a 58% Fe cargo priced against the 61% index?
As the 61% Fe CFR China index less a differential (the Platts IODEX basis moved from 62% to 61% Fe on 2 January 2026), and the differential is not a straight-line 3%. Each unit of Fe below 61% is deducted at a value-in-use rate, then silica, alumina and phosphorus above the standard cut further, and loss on ignition above the standard cuts again because that weight leaves in the furnace. A high-alumina, high-P 58% ore can trade at a deep discount to what its Fe alone implies; a clean 60% ore with low gangue at a shallow one. Send the full chemistry and we will price the differential, not just the Fe.
What is the transportable moisture limit and why does it hold a cargo?
Fines are a cargo that can liquefy under the IMSBC Code if the moisture is above the transportable moisture limit (TML) for that ore. The shipper must certify the TML by a recognised test and declare the actual moisture within seven days of loading; the master can refuse to load if the moisture is above it, and in the monsoon at Indian and Malaysian load ports it often is. Build the moisture test into the loading plan and the price adjustment clause, and stockpile under cover or drain before loading, or the vessel waits at your cost.
Do you broker Australian and Brazilian ore?
Not the majors' term tonnage; they sell it themselves. CBIL brokers the second tier — spot and short-term parcels from India's non-captive east-coast exporters, South African junior miners and Malaysia's own mines — and prices them against the 61% Fe index. Most ore declared as a Malaysian export is Brazilian ore re-shipped from Vale's Teluk Rubiah terminal and sold by Vale, so a 'Malaysian' offer is checked for its mine of origin before it is priced. Where a trader holds a resale parcel of Australian or Brazilian origin we will work it, but that is a trader position, not a mine allocation, and we say so.
What parcel sizes and load ports do you work?
Supramax and Ultramax (50–65,000 MT) out of Paradip, Haldia, Visakhapatnam and Kuantan, which is how most of the China-bound ore loaded at Paradip between June and September 2026 moved; Panamax and Capesize out of Saldanha where both ends take the draft. On FOB and CFR terms. Because CBIL also runs a chartering desk, we quote the freight leg with the cargo so you see the CFR and FOB numbers side by side on the same day.
Ready to source Iron Ore Fines?
Send your quantity, specification, preferred Incoterms and destination port. Qualified requirements receive a workable offer against verified supply.
Have Iron Ore Fines to sell? Submit an offer — we'll match it against live buyer demand.
More in Iron Ore, Pig Iron & DRI
Iron Ore Lumps & Pellets
Direct-charge lump and blast-furnace / DR-grade pellets by Fe, tumble index and CCS
Pig Iron
Basic, foundry and nodular pig iron by Si, Mn, P and S for melt shops and foundries
DRI & HBI (Direct Reduced Iron)
Hot briquetted iron and DRI by metallisation, carbon and gangue for EAF melt shops
Industrial Mill Scale
High-density iron oxide byproduct (65–70% Fe) for blast furnace sinter burdens, cement manufacture and ferroalloys
Iron Ore Pellets (BF & DR Grade)
Blast-furnace pellets at 63–65% Fe and direct-reduction pellets at 67% Fe and above, priced as a premium over the fines index
High-Purity Pig Iron (HPPI)
Low-manganese, low-phosphorus base iron for ductile castings, a co-product of titania slag smelting