Iron Ore Pellets (BF & DR Grade)
Blast-furnace pellets at 63–65% Fe and direct-reduction pellets at 67% Fe and above, priced as a premium over the fines index
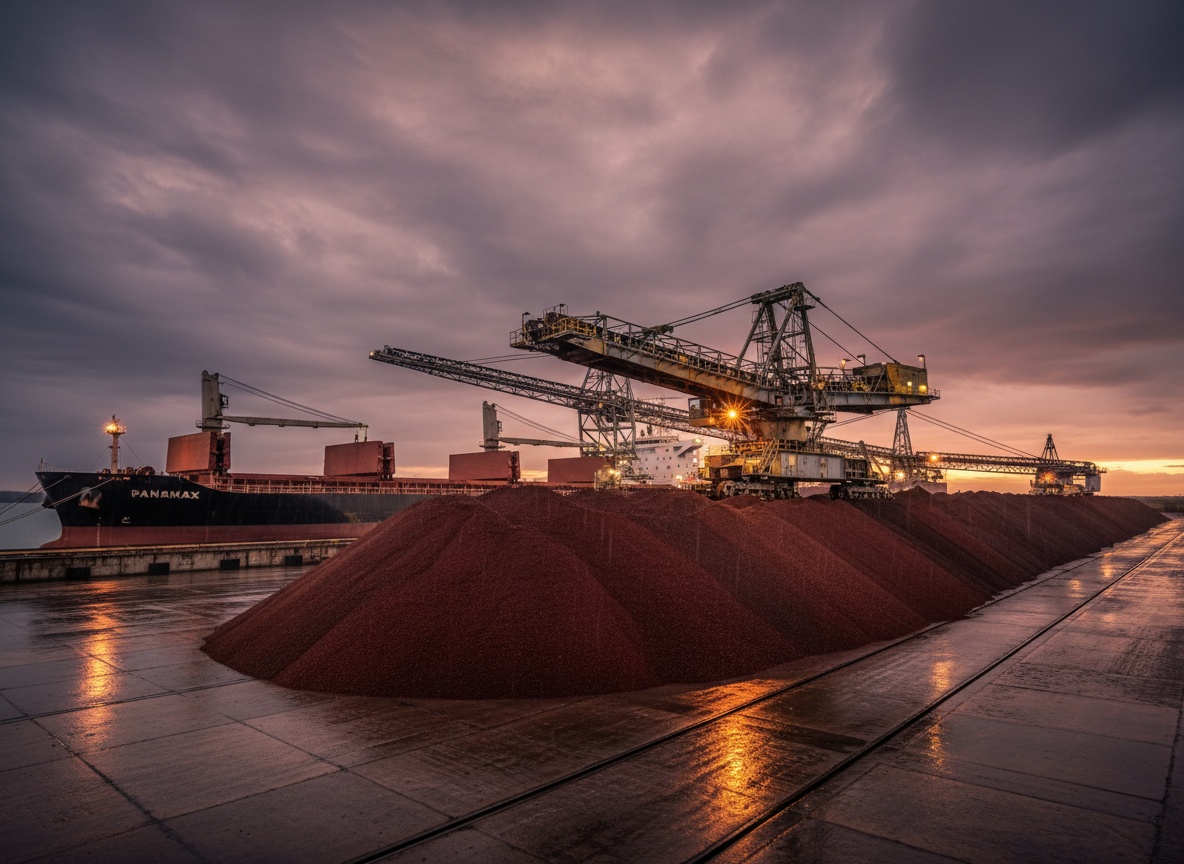
A pellet is a manufactured burden: concentrate balled and fired into 9 to 16 mm spheres that a furnace can charge without sintering. Blast-furnace grade runs 63 to 65% Fe and is bought on cold compression strength (250 daN per pellet is the working floor), tumble index, reducibility and, for fluxed pellets, basicity. Direct-reduction grade runs 67% Fe or better with silica plus alumina of 3% or less and low phosphorus, because a reduction shaft makes no slag and every unit of gangue goes on to the electric-arc furnace. The two are priced separately, each as a premium over the 65% Fe fines index. In 2026 the Atlantic blast-furnace pellet premium averaged about USD 28 per tonne in the first quarter and USD 31 in the second, and the largest producer's third-quarter contract premium was USD 40 per dry tonne; the direct-reduction premium, assessed at 67.5% Fe, was about USD 42 and USD 43. Realised pellet prices at the largest seller were about USD 137 per tonne in the second quarter. Supply is concentrated. Brazil exported 26.3 million MT in 2024, Sweden 16.0 million, Canada 13.9 million, Oman 10.3 million from the pellet plant at Sohar, which has 9 million MT a year of capacity, and India 8.2 million. In 2026 supply tightened: the Sohar plant was suspended in March and had only partly resumed by late June, making about 200,000 MT in the second quarter against 1.74 million MT a year earlier; a Swedish pellet line is shut from mid-April to November, taking about 2 million MT out of shipments; and India's pellet exports fell 53% to 3.47 million MT in the year to March 2026 as its own mills took the tonnage. Pellet plants on the Gulf coast, which shipped more than 10 million MT in 2024, are behind the Strait of Hormuz, severely restricted since 28 February 2026, and are not offered as active supply.
The buyers are easier to map than the sellers. China imported 23.0 million MT in 2025, with its intake of Indian pellets falling from 7.76 million to 3.72 million MT and Swedish and Ukrainian tonnage rising. Germany imported 11.2 million MT, 43% from Sweden and 38% from Canada. Egypt imported 8.2 million MT, mainly from Brazil, Oman and Sweden, for its direct-reduction plants. Japan took 6.0 million MT, the United States 4.9 million, Türkiye 3.7 million and Belgium 3.4 million. CBIL brokers Indian merchant pellets in part cargoes and Supramax lots from Paradip, Haldia and Visakhapatnam, and trader resale parcels of Brazilian, Swedish, Canadian and Omani pellets, against SGS, Intertek or Bureau Veritas certification of chemistry, size, cold compression strength, tumble and abrasion indices and moisture, sampled at the load port to ISO 3082. The mine and pellet plant of origin are named on every offer and checked against the certificate of origin before a price is given. Because CBIL also runs a chartering desk, LaycanDesk, the freight is quoted with the cargo on FOB and CFR terms.
See also: Iron ore pellets CFR India (Paradip, Vizag, Hazira) · Iron ore lump, the other direct-charge ore · DRI and HBI, what DR-grade pellets become · Iron ore fines and the 61% Fe index
Need the ship as well? Our chartering desk prices Chattogram to Vietnam mill scale freight on LaycanDesk.
Excluded origins are not offered, including product re-exported, blended or re-processed through a third country. Every lot moves with a certificate of origin naming the producing plant, mine or grower country, and nothing is quoted before the seller and loading point are known.
Indicative reference
$110–175 USD / MT
as at September 2026
Reference level only — not an offer, and reviewed quarterly. Levels shown are as at September 2026. Firm pricing is quoted per RFQ, subject to volume, terms and inspection.
Typical Specification
Specifications are indicative and adjusted to the agreed contract and destination requirements. Final spec confirmed on COA / SGS.
Available Grades
Applications
- Blast-furnace burden (direct charge)
- Direct-reduction shafts (Midrex / Energiron)
- Mills without a sinter plant
- Burden mix to cut sinter and coke rate
Category
Metals & Recycled Scrap
Incoterms
FOB · CFR
Pricing basis
USD / MT
Inspection
SGS / Intertek at load port
Iron Ore Pellets (BF & DR Grade) — buyer questions
How are pellets priced?
As the 65% Fe fines index plus a pellet premium. Blast-furnace and direct-reduction pellets carry separate premiums: in 2026 the Atlantic blast-furnace premium was about USD 28 per tonne in the first quarter and USD 31 in the second, with a third-quarter contract premium of USD 40 per dry tonne, and the direct-reduction premium at 67.5% Fe was about USD 42 to 43. Indian merchant pellets trade at a fixed CFR China price that moves with the same index. Fe above or below the base is adjusted pro rata, and penalties apply to silica, alumina and phosphorus above the contract limits.
Who buys pellets in China, and what changed?
Coastal blast-furnace mills that use pellets to raise productivity or to cut sinter output during emission curbs. China imported 23.0 million MT in 2025, about the same as in 2024, but its intake from India fell from 7.76 million to 3.72 million MT as Indian mills kept the pellets at home, a gap of roughly 340,000 MT a month. Swedish tonnage rose from 169,000 to 684,000 MT and Ukrainian from 403,000 MT to 1.15 million MT. A buyer there contracts on CFR main port with the load-port certificate governing.
Who buys in Europe and Türkiye?
Germany is the largest European importer at 11.2 million MT in 2025, 43% from Sweden and 38% from Canada, with Brazil at 12%; Ukrainian shipments fell from 985,000 to 198,000 MT and US shipments from 1.11 million to 381,000 MT in the year. Belgium imported 3.4 million MT, mostly Swedish and Brazilian. Türkiye imported 3.7 million MT, with Brazilian tonnage rising from 168,000 to 587,000 MT and Norwegian pellets appearing at about 495,000 MT. European mills moving to direct reduction will need DR-grade rather than blast-furnace pellets.
Who buys DR-grade pellets?
Direct-reduction plants, which are the strictest pellet buyers: Egypt imported 8.2 million MT of pellets in 2025, 43% from Brazil, with Oman, Sweden and Canada behind, and plants in Libya, Algeria, Trinidad and Southeast Asia buy the same grade. Several North African producers have built their own pelletisers and now buy pellet feed instead. Trinidad's landed value in 2025, about USD 174 per tonne against a world median near USD 128, shows what DR quality and a long haul cost.
Does India import pellets as well as export them?
Yes. India exports merchant pellets from its east coast, with no export duty on pellets, and its coastal steel plants also import pellets and ore when landed cost beats rail freight from the interior. CBIL works Indian import enquiries only with the pellet plant of origin named and documented on the certificate of origin, and declines parcels whose origin cannot be shown from the producing plant's own papers.
Ready to source Iron Ore Pellets?
Send your quantity, specification, preferred Incoterms and destination port. Qualified requirements receive a workable offer against verified supply.
Have Iron Ore Pellets to sell? Submit an offer — we'll match it against live buyer demand.
More in Iron Ore, Pig Iron & DRI
Iron Ore Fines
Second-tier fines 58–65% Fe priced off the 61% Fe index with a differential
Iron Ore Lumps & Pellets
Direct-charge lump and blast-furnace / DR-grade pellets by Fe, tumble index and CCS
Pig Iron
Basic, foundry and nodular pig iron by Si, Mn, P and S for melt shops and foundries
DRI & HBI (Direct Reduced Iron)
Hot briquetted iron and DRI by metallisation, carbon and gangue for EAF melt shops
Industrial Mill Scale
High-density iron oxide byproduct (65–70% Fe) for blast furnace sinter burdens, cement manufacture and ferroalloys
High-Purity Pig Iron (HPPI)
Low-manganese, low-phosphorus base iron for ductile castings, a co-product of titania slag smelting